
Fundamentals
Yen Carry Trade: Why It Moves Markets and How It Unwinds
The yen carry trade explained: why traders borrow cheap yen to hold higher-yielding assets, how the numbers work, and what happens when it unwinds.
11 min read
Read more →
The carry trade explained: how holding a high-rate currency against a low-rate one earns a daily swap, and why the trade unwinds all at once.
The carry trade is one of the oldest and best-known ideas in currency markets. You borrow a currency with a low interest rate and hold one with a higher rate. Then you collect the gap between the two for as long as the position stays open.
It can pay quietly for years, then lose more than a year of income in a few days. This guide explains the carry trade meaning and works through the numbers on a small account. It then shows why the trade unwinds all at once, what a reverse carry trade is, and where gold fits in.
Every forex position is long one currency and short another. When you hold it overnight, you earn interest on the currency you own and pay interest on the one you owe. A carry trade sets this up on purpose, so the interest you earn is larger than the interest you pay.
Traders use two names for the legs. The funding currency is the low-rate one you borrow, or sell. The target currency is the higher-rate one you buy and hold. The word carry comes from finance, where it means the income a position pays you just for holding it.
What each variable means:
The gap between the two rates is the interest rate differential. It applies to the notional, the full size of the position. That one detail explains both the appeal of the carry trade and the way it breaks.
Which currencies play each role changes with policy. For long stretches, low-rate currencies such as the Japanese yen and the Swiss franc have been popular for funding. Higher-yielding currencies, including several commodity and emerging-market currencies, have often been the targets.
The lesson on carry and rate differentials covers the mechanics in course form. The lesson on interest rates and why currencies follow them explains where the rates come from.
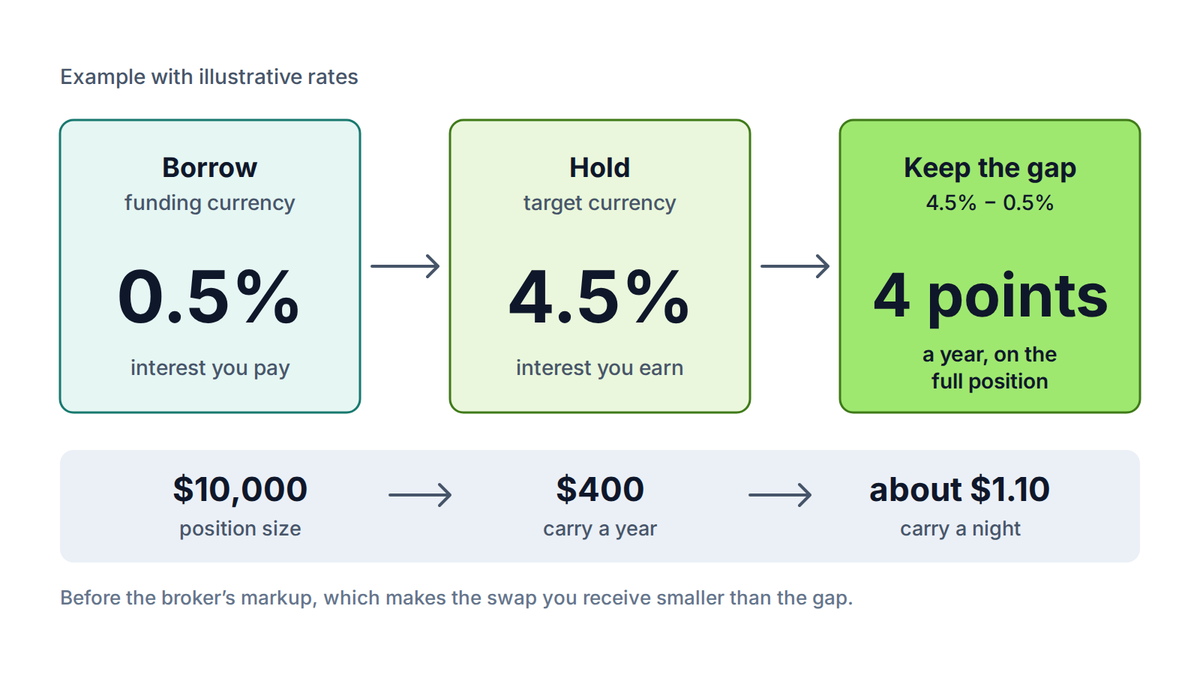
Take an example with round numbers. Say the US dollar pays 4.5% and the Japanese yen pays 0.5%, a gap of 4 percentage points. These are illustrative rates for the arithmetic, not today's rates or a forecast.
To earn that gap, you would buy USD/JPY at 150.00, which means buying dollars and selling yen. One lot (the standard trade size) of USD/JPY is $100,000, so 0.10 lot is a $10,000 position.
At 1:500 leverage (borrowed exposure that lets a small deposit control a larger position), that position needs only $20 of margin. Margin is the deposit your broker sets aside to keep a position open, and the margin calculator gives the same figure.
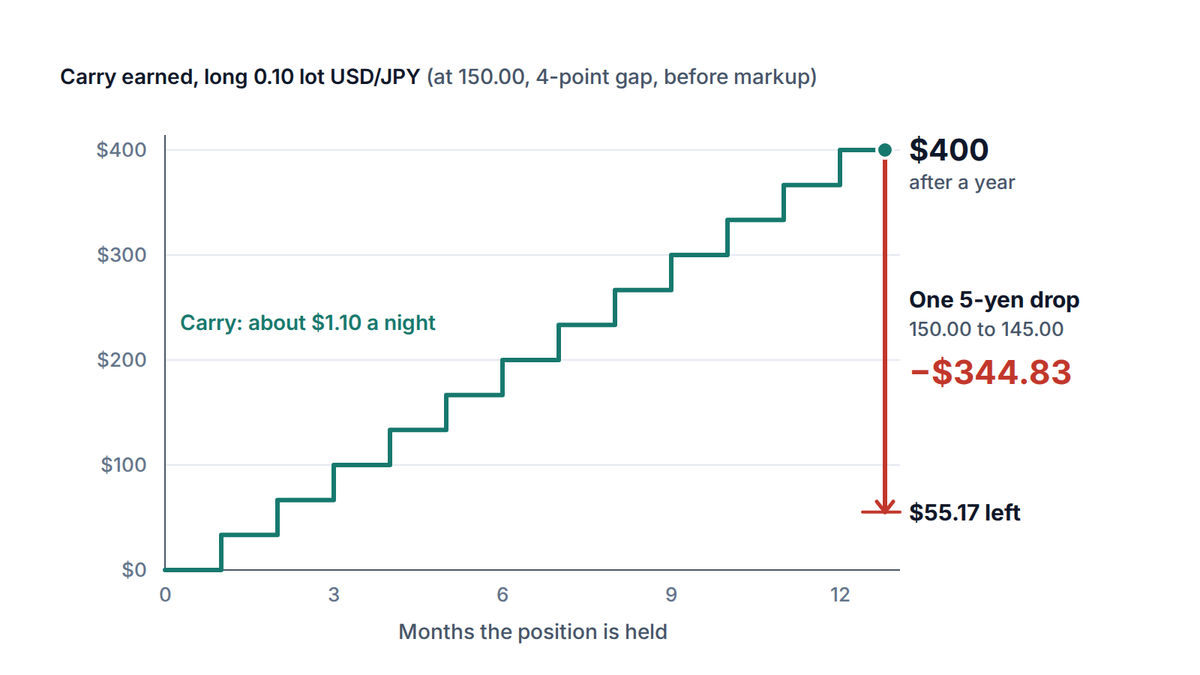
The carry is 4% of $10,000, or $400 a year. Spread over 365 nights, that is about $1.10 a night, or $32.88 over 30 nights. The table shows the same trade at three sizes on the site's $2,400 example account.
| Position | Notional | Margin at 1:500 | Carry per night | Carry per year | Per year, share of $2,400 |
|---|---|---|---|---|---|
| 0.01 lot | $1,000 | $2 | $0.11 | $40 | 1.7% |
| 0.10 lot | $10,000 | $20 | $1.10 | $400 | 16.7% |
| 1.00 lot | $100,000 | $200 | $10.96 | $4,000 | 166.7% |
The last row shows the lure. On $200 of margin, a full lot earns $4,000 a year, more than one and a half times the whole account. Leverage makes carry look large because the interest is paid on the notional, not on your deposit. The same leverage applies to every move in the exchange rate.
As a retail trader, you don't receive the textbook gap. You receive swap (the interest adjustment your broker applies to positions held overnight), and it includes a markup in the broker's favor.
Swap is applied at the daily rollover, usually 5 p.m. New York time. That is 21:00 UTC during US daylight saving time and 22:00 UTC otherwise. A position closed before the rollover earns or pays no swap at all.
Check before you count on it
Your platform's contract specification shows two figures, swap long and swap short. The guide to reading a broker's gold specs shows where to find them. The lesson on what a trade really costs explains how swap adds to your other costs.
In textbook theory, the carry trade shouldn't pay. A rule called uncovered interest parity says the higher-yielding currency should fall by roughly the rate gap over time. If it did, the currency loss would cancel the interest you collect.
In practice, that often hasn't happened over long, calm stretches. High-yielding currencies have frequently held steady or even risen while paying their extra interest. Economists call this the forward premium puzzle, and it is the reason the carry trade exists at all.
The trade also feeds itself while it works. Each new carry trader buys the target currency and sells the funding currency. That flow pushes the target currency up, which adds a price gain on top of the interest and draws in more traders.
Three conditions keep it going:
Each of these can change quickly. A central bank decision can shift the expected rate gap in an afternoon. The article on FOMC and gold shows how fast a rate surprise is repriced. A volatility spike can turn a year of steady income into a loss within days.
Traders say the carry trade goes up the stairs and down the elevator. It earns a little every night, then loses a lot very quickly. That shape is built into the trade, not bad luck.
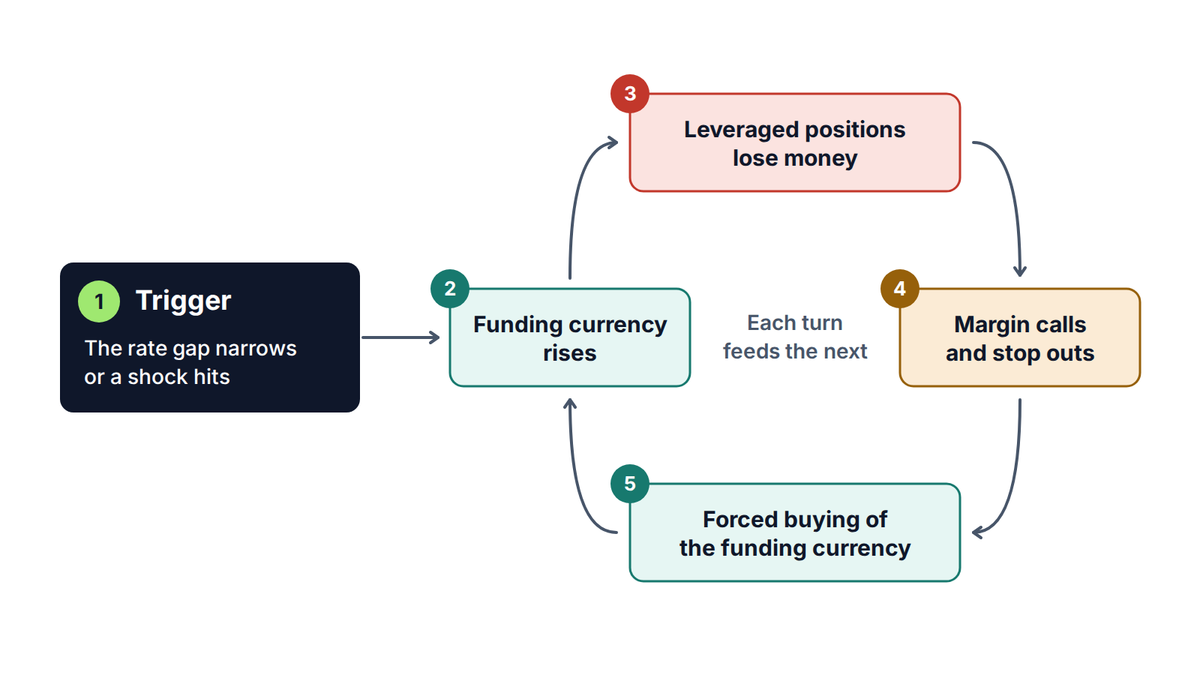
The unwind follows a loop, and each step makes the next one more likely:
The arithmetic shows why the loop bites. In the example, USD/JPY falling from 150.00 to 145.00 is a 5-yen drop, about 3.3%. The profit/loss calculator puts the loss on 0.10 lot at $344.83.
At $1.10 a night, that wipes out about 315 nights of carry, more than ten months of income. A full year of carry is $400, so one move of a few percent would leave just $55.17 of it.
| Position | Carry per year | Loss on a 5-yen drop | Loss, share of $2,400 |
|---|---|---|---|
| 0.01 lot | $40 | $34.48 | 1.4% |
| 0.10 lot | $400 | $344.83 | 14.4% |
| 1.00 lot | $4,000 | $3,448.28 | 143.7% |
At 1.00 lot, the same drop costs more than the whole $2,400 account. Your broker would stop you out well before the move finished. The position that earned 166.7% a year on paper can end the account in a few days.
The yen carry trade gave a sharp example in the summer of 2024. On 31 Jul 2024, the Bank of Japan raised its policy rate to around 0.25%, from a range of 0 to 0.1%. On 2 Aug 2024, a weak US jobs report showed 114,000 new jobs and unemployment rising to 4.3%.
Both pointed to a narrower gap between US and Japanese rates. The Federal Reserve's daily noon rates show USD/JPY at 161.73 on 10 Jul 2024 and 143.95 on 5 Aug 2024, a fall of about 11%. On 0.10 lot, that slide cost $1,235.15, about half of a $2,400 account.
On 5 Aug 2024, Japan's Nikkei 225 stock index fell 12.4% in a single session. The VIX volatility index closed at 38.57, up from 16.36 on 31 Jul. Gold was sold too, as traders raised cash for margin calls elsewhere.
The Bank for International Settlements (BIS) estimated FX carry trades at roughly 40 trillion yen, about $250 billion, going into the event. Markets steadied within days. The BIS described the episode as volatility amplified by deleveraging and higher margin requirements. The shape is the one to remember: a slow build-up, then a fall of about 11% in under four weeks.
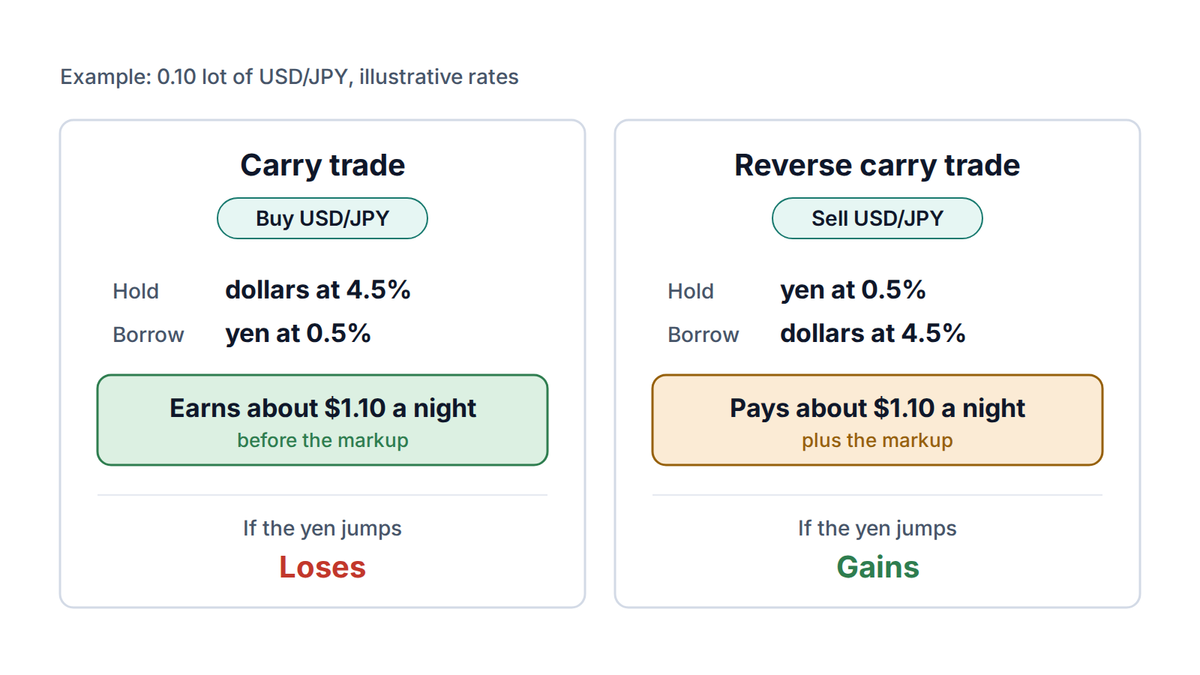
The term reverse carry trade has no single official definition, and you'll see it used in two ways.
The second meaning is a bet that the currency move will outrun the cost. In the example, selling 0.10 lot of USD/JPY would pay about $1.10 a night before the markup, or $32.88 over 30 nights. The arithmetic runs against you every night, so timing matters far more than in a classic carry trade.
Traders take that side when they expect the rate gap to narrow or expect a risk-off move, when investors cut risky positions together. The lesson on risk-on and risk-off explains why funding currencies tend to rise when that happens.
Gold pays no interest. A long XAU/USD position (gold priced in US dollars) is financed like a loan in dollars, so on most platforms it pays swap every night. In carry terms, holding gold is a negative-carry trade, much like the second kind of reverse carry.
That is one reason interest rates matter so much to gold. When dollar rates rise, holding gold costs more, both on your swap line and for every investor weighing gold against cash. In an unwind, gold isn't always a shelter either, because traders who need cash for margin calls sell whatever they can.
For most retail traders, carry is a cost to manage, not a strategy to build around. At 0.10 lot it is about a dollar a night, while the 5-yen drop in the example costs as much as ten months of it. A few habits keep it in proportion:
Try it now
Enter the pair, price, lot size and leverage to see the notional and the margin a position ties up. Then run a move against you through the Profit/Loss Calculator and compare it with the carry.
Risk warning
Leverage magnifies currency moves in both directions, and carry trades are usually run with a lot of it. An unwind can gap price past your stop, and with high leverage it can take you to a stop out. Trading CFDs (contracts for difference, which track a price without delivering the asset) can lose you more than you planned, including your whole deposit.
You borrow, or sell, a currency with a low interest rate and buy one with a higher rate. You earn the difference between the two rates for every night you hold the position. The risk is that the exchange rate moves against you by more than the interest you collect.
It can be, but rarely at small sizes. You receive swap after the broker's markup, and at 0.10 lot a 4-point gap pays about $1.10 a night. Price moves usually decide the result, so carry works better as a cost to track than as a reason to trade.
People use the term in two ways. It can mean the unwind of carry trades, when traders buy back the funding currency. It can also mean a deliberate position that buys the low-rate currency, pays swap every night and bets on a currency gain.
They are crowded, leveraged and all on the same side. When the funding currency starts to rise, losses trigger margin calls and stop outs, and closing those positions means buying the funding currency. That buying pushes it higher and forces the next round of closing.
The PipsMorrow Team
A team of writers covering XAU/USD gold trading education. We focus on explaining the mechanics and risk management in a structured way, with no trade signals and no promotion of any specific broker.
Last updated
The yen carry trade explained: why traders borrow cheap yen to hold higher-yielding assets, how the numbers work, and what happens when it unwinds.
11 min read
Read more →Gold price vs interest rates: why the real yield, not the headline rate, drives gold, where that link broke after 2022, and how to size trades around it.
10 min read
Read more →Gold and financial sanctions after 2022: the Russian reserve freeze, the LBMA refinery ban, why central banks turned to gold, and what it means for XAU/USD.
8 min read
Read more →Build on this article with the full gold trading curriculum, ordered from the basics to advanced topics, free.

